Adapted from the original Todo Insurance blog. Educational information: verify current rules and documents before applying for or changing coverage.
The same Medicare foundation, two ways to receive care
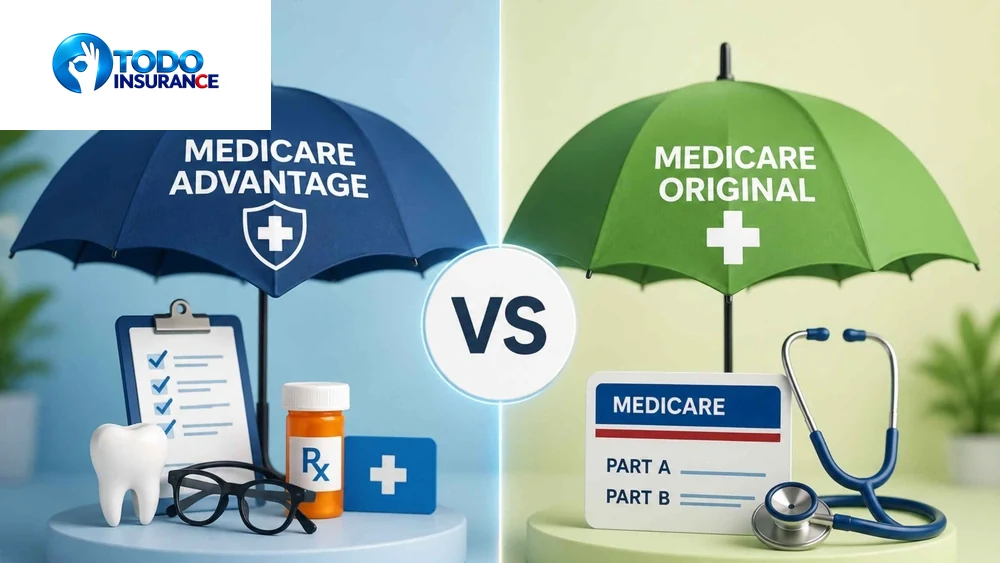
Original Medicare combines federally administered Parts A and B. Medicare Advantage, or Part C, is an alternative in which a Medicare-approved private insurer administers those benefits. You remain enrolled in Medicare under either route. The choice depends on your doctors, prescriptions, travel and the total cost you can manage.
How Parts A, B, C and D fit together
Part A helps with hospital care; Part B helps with medical and outpatient services. Part D is prescription drug coverage. Medicare Advantage delivers A and B benefits through a private plan, and many plans include D. Plans must cover A and B services, with specific rules for certain services, including hospice care and clinical research studies.
| Consideration | Original Medicare | Medicare Advantage |
|---|---|---|
| Administration | Federally administered Parts A and B. | Medicare-approved private plan. |
| Providers | Providers accepting Medicare in the U.S. | Plan-specific network and rules. |
| Prescriptions | Generally separate Part D coverage. | Part D included in many plans, but not all. |
| Additional benefits | Routine dental, eyewear and hearing care generally not included. | May be offered, subject to limits and conditions. |
| Out-of-pocket maximum | No annual limit of its own without other coverage. | Limit for A and B services; prescriptions separate. |
| Medigap | May supplement certain costs, subject to eligibility. | Does not pay Advantage cost sharing. |
The provider network changes the experience
With Original Medicare, you can use providers who accept Medicare in the United States. Advantage plans have networks and rules based on whether they are HMOs, PPOs or another type. A doctor accepting Medicare does not automatically participate in every Advantage plan. Check providers, hospitals, referrals and prior authorization in the exact plan and confirm directly with the provider.
Compare the full annual cost
Include the Part B premium, any additional plan or other policy premiums, deductibles, copayments and coinsurance. An Advantage option with a $0 additional premium, if offered, does not mean all care is free. How often you receive care and the treatment you need may change which route makes more sense.
The out-of-pocket limit has a specific scope
Original Medicare has no annual out-of-pocket maximum for its services without other coverage. Advantage has a limit for covered Part A and Part B services. Prescriptions follow separate rules; do not assume those costs count toward the same maximum. Compare in-network and out-of-network limits when applicable.
Prescriptions and extra benefits
Review each prescription by name, dose, cost tier, pharmacy and authorization requirements. Many Advantage plans include Part D; with Original Medicare it is usually purchased separately. Dental, vision, hearing, transportation, telehealth and wellness benefits may be offered in certain plans, but allowances and conditions vary. An extra benefit does not replace access to a specialist or medicine you need.
Medigap is a separate decision
A Medigap policy may help pay certain Original Medicare costs, depending on the plan. It does not pay Medicare Advantage cost sharing. Enrollment and guaranteed-issue rights differ; do not assume you can buy any Medigap policy at any time without health underwriting. Check your rights before leaving existing coverage.
If you travel or receive care in different areas
Original Medicare offers broad access to providers accepting Medicare within the United States. For routine care with Advantage, check the network and out-of-area rules. Emergency and urgently needed care have protections, but that is not unlimited coverage for all care while traveling. International travel needs a separate review.
Enrollment and plan changes
You generally need active Parts A and B and must live in the plan’s area to join Advantage. Medicare’s annual enrollment runs October 15 through December 7. The January 1 through March 31 Medicare Advantage period is for people already enrolled in Advantage and permits certain changes, not general enrollment from Original Medicare. Initial or special periods may also apply. Confirm eligibility and effective dates at Medicare.gov.
Bring your actual circumstances to the comparison
If you see several specialists, check each before switching. If you take expensive prescriptions, calculate their costs separately. If you travel often, review routine care outside your area. If you want a lower premium, also compare what you would pay when using care. There is no single winner for everyone.
Before making a decision
Confirm Parts A and B, your address and eligibility. List doctors, hospitals, prescriptions and your pharmacy. Compare annual costs, limits, networks and authorizations. Read the Summary of Benefits and Evidence of Coverage. Check the enrollment period and any Medigap rights. Do not cancel a policy until you know when the new coverage takes effect.